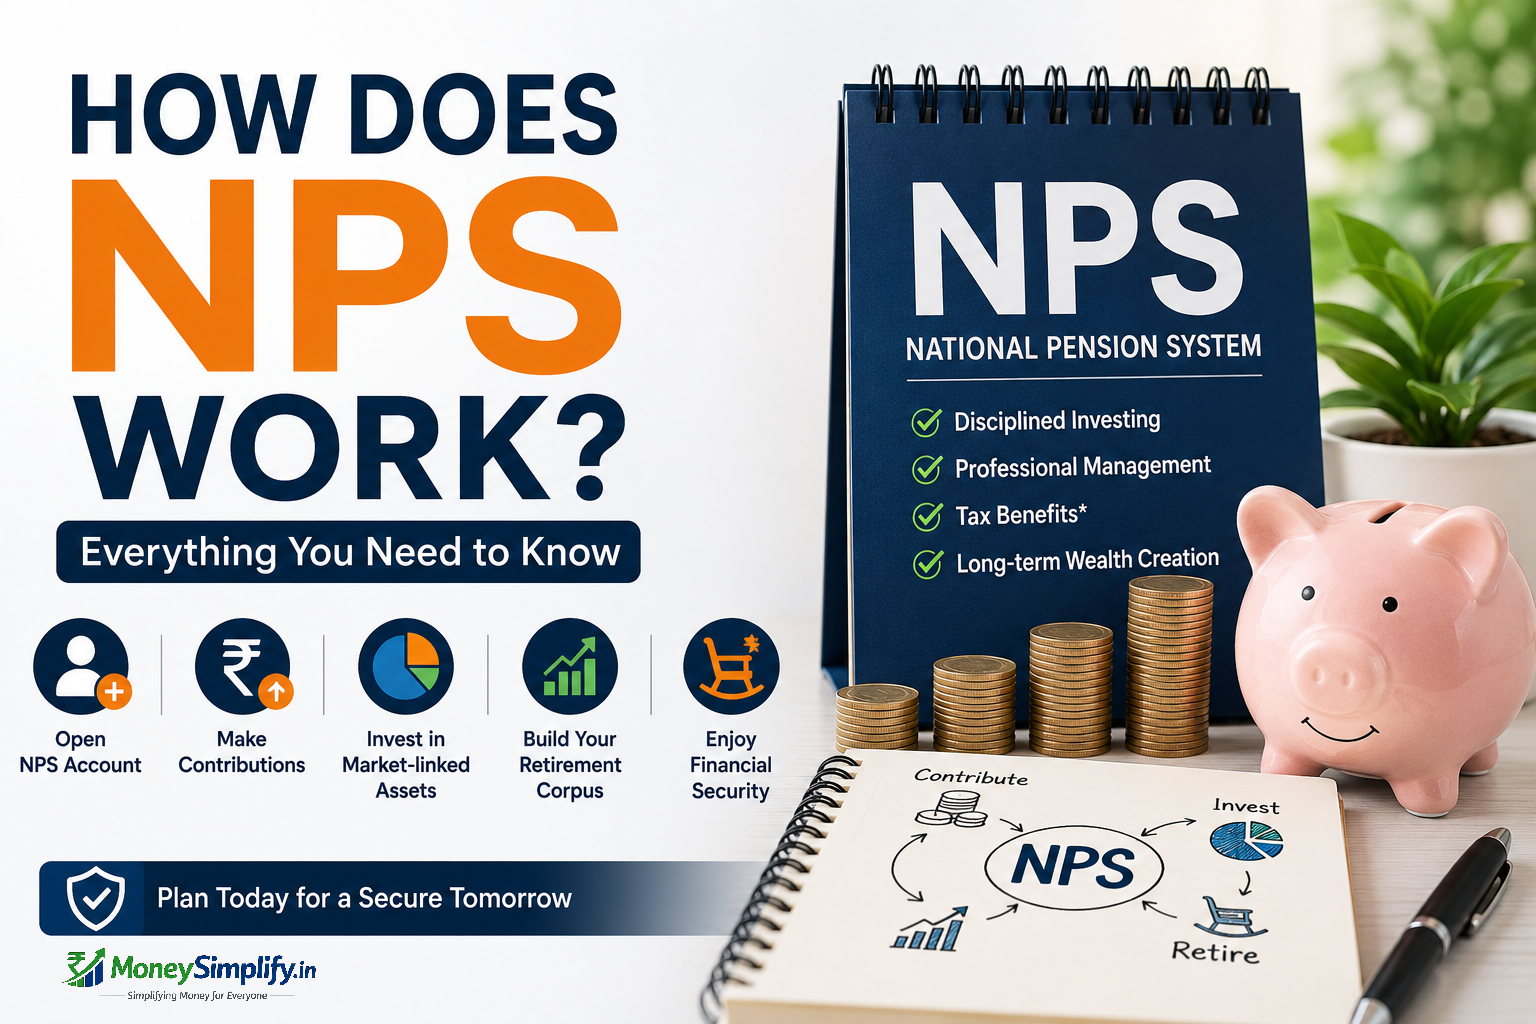
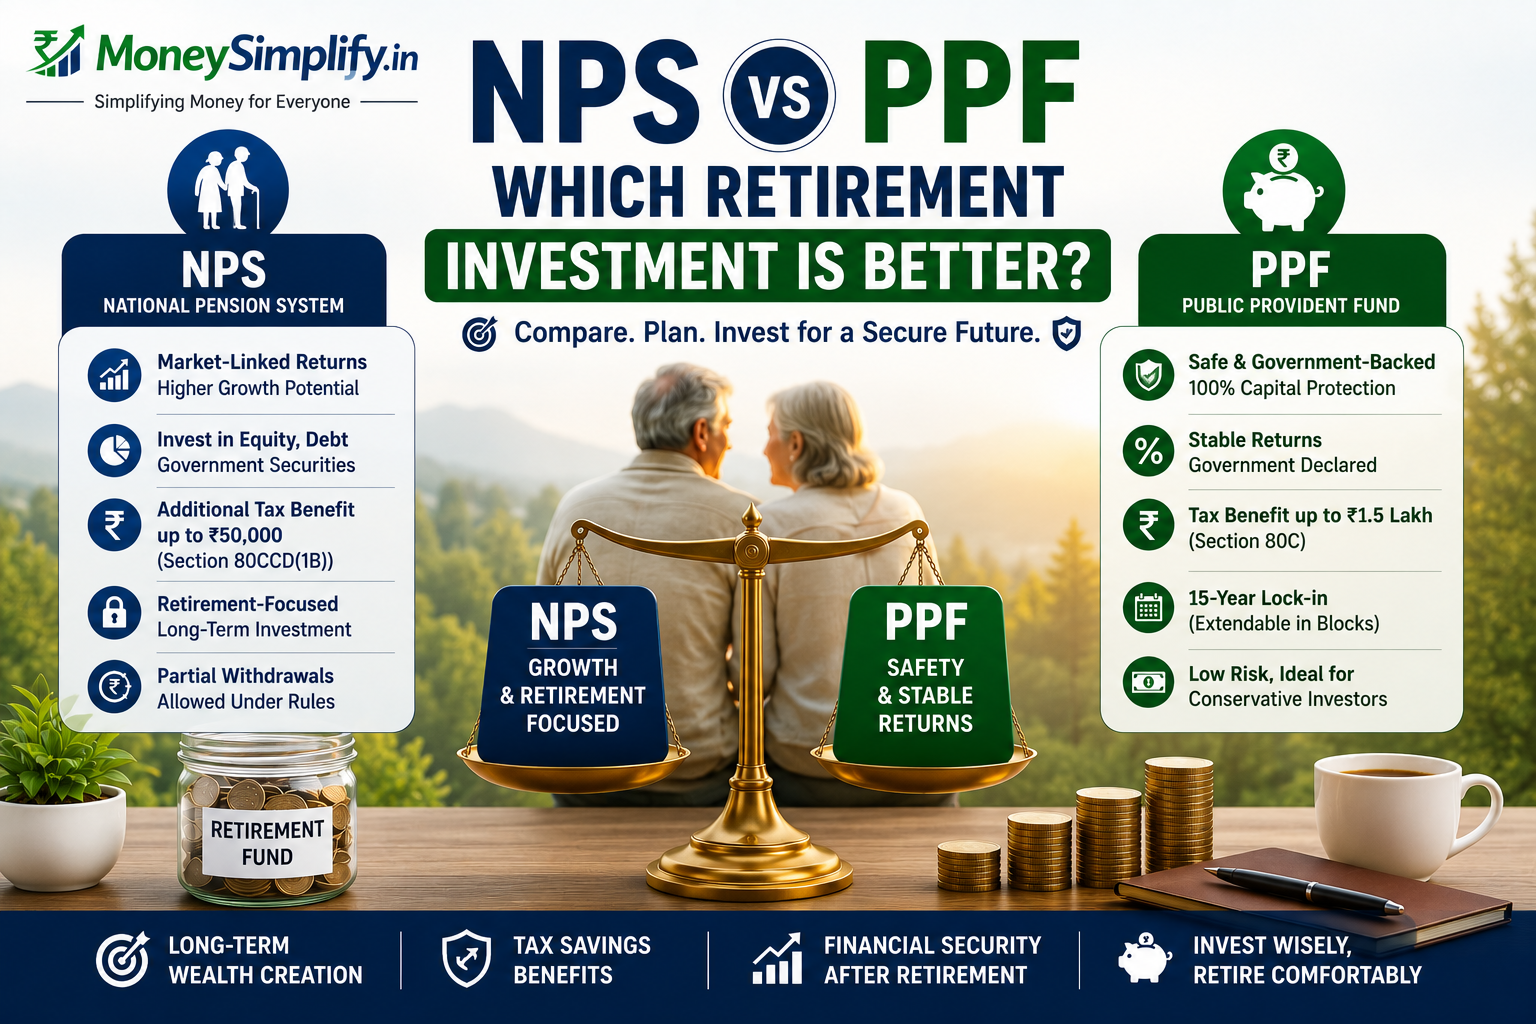
Planning for retirement is one of the most important financial decisions you’ll make.
Two of the most popular long-term investment options in India are the National Pension System (NPS) and the Public Provident Fund (PPF).
Both help investors build wealth over time and offer tax benefits, but they differ in terms of risk, returns, flexibility, and withdrawal rules.
So, which investment is better for your retirement goals?
The answer depends on factors such as your age, risk tolerance, investment horizon, and financial objectives.
In this guide, we’ll compare NPS and PPF in detail to help you make an informed investment decision.
What Is NPS?
The National Pension System (NPS) is a government-regulated retirement savings scheme designed to help individuals build a retirement corpus through regular contributions.
NPS invests in a combination of:
- Equity
- Corporate bonds
- Government securities
- Alternative investment assets (where applicable)
The allocation depends on the investment option selected and applicable regulations.
The primary objective of NPS is to provide financial security after retirement.
What Is PPF?
The Public Provident Fund (PPF) is a government-backed long-term savings scheme.
It is designed for investors who prefer:
- Stable returns
- Capital safety
- Long-term savings
- Tax-efficient investing
Unlike NPS, PPF does not invest in equity markets.
Interest rates are declared periodically by the Government of India.
NPS vs PPF: Quick Comparison
| Feature | NPS | PPF |
|---|---|---|
| Investment Type | Retirement Scheme | Savings Scheme |
| Risk Level | Moderate | Low |
| Return Type | Market-Linked | Government-Declared |
| Tax Benefits | Available | Available |
| Equity Exposure | Yes | No |
| Lock-In | Until Retirement (subject to applicable rules) | 15 Years |
| Suitable For | Long-Term Retirement Planning | Conservative Long-Term Savings |
Tax Benefits
Both NPS and PPF offer tax benefits under applicable tax laws.
NPS
Eligible contributions may qualify for deductions under the relevant provisions of the Income Tax Act.
In certain cases, additional tax benefits may also be available, subject to prevailing regulations.
PPF
PPF investments qualify for deductions under Section 80C, subject to the applicable deduction limit.
Investors should always verify the latest tax rules before making investment decisions.
Risk Comparison
One of the biggest differences between NPS and PPF is risk.
NPS
Since NPS invests partly in equity markets, returns can fluctuate depending on market performance.
This means:
- Higher growth potential
- Higher volatility
- Market-related risk
PPF
PPF is backed by the Government of India.
Returns are declared periodically and are generally considered more stable than market-linked investments.
Investors seeking predictable returns often prefer PPF.
Returns Comparison
It is impossible to predict future returns.
However, the nature of returns differs.
NPS
Returns depend on:
- Asset allocation
- Equity performance
- Debt market performance
- Fund management
PPF
Returns depend on the interest rate declared by the Government of India.
They are not directly linked to stock market performance.
Liquidity and Lock-In Period
NPS
NPS is primarily designed for retirement.
Withdrawals are governed by applicable rules and regulations.
Partial withdrawals may be permitted under certain conditions.
PPF
PPF has a:
15-year lock-in periodPartial withdrawals and loan facilities may be available after specified periods, subject to prevailing rules.
Who Should Choose NPS?
NPS may be suitable for investors who:
✓ Have a long investment horizon.
✓ Are comfortable with market-linked investments.
✓ Want to build a retirement corpus.
✓ Seek the potential for higher long-term returns.
Who Should Choose PPF?
PPF may be suitable for investors who:
✓ Prefer low-risk investments.
✓ Value government-backed security.
✓ Want stable long-term savings.
✓ Are comfortable with a long lock-in period.
Can You Invest in Both?
Yes.
Many financial planners recommend combining NPS and PPF as part of a diversified retirement strategy.
For example:
- NPS may provide growth through market-linked investments.
- PPF may provide stability through government-backed returns.
Together, they can help balance risk and long-term wealth creation.
In the next section, we’ll compare costs, withdrawal rules, common mistakes, frequently asked questions, and help you decide whether NPS, PPF, or a combination of both is the better choice for your retirement goals.
Charges and Costs
Understanding the costs associated with an investment is important because they can affect long-term returns.
NPS
NPS generally has low fund management charges compared to many other investment products.
However, investors may also encounter charges related to account maintenance and transactions, depending on the service provider and applicable regulations.
PPF
PPF is a government-backed savings scheme and does not involve fund management charges like market-linked investment products.
Investors should always review the latest rules and fee structure before opening an account.
Withdrawal Rules
NPS
NPS is intended primarily for retirement planning.
Withdrawals are governed by the rules applicable at the time of withdrawal.
Partial withdrawals may be permitted under certain conditions, while the remaining corpus is generally subject to retirement-related withdrawal rules.
PPF
PPF has a 15-year maturity period.
Partial withdrawals and loan facilities may be available after specified years, subject to the prevailing rules and eligibility conditions.
NPS vs PPF: Which Is Better?
The answer depends on your financial objectives.
Choose NPS If:
- You have a long-term retirement goal.
- You are comfortable with market-linked investments.
- You want the potential for higher long-term returns.
- You can tolerate short-term market fluctuations.
Choose PPF If:
- You prefer capital safety.
- You want government-backed returns.
- You are a conservative investor.
- You value predictable long-term savings.
Choose Both If:
Many investors choose to invest in both NPS and PPF.
This approach allows them to combine:
- Growth potential through NPS.
- Stability through PPF.
A diversified retirement strategy may help balance risk and long-term financial security.
Common Mistakes to Avoid
Choosing Only Based on Returns
Higher historical returns do not necessarily guarantee better future performance.
Always consider your:
- Financial goals
- Risk tolerance
- Investment horizon
Ignoring Retirement Planning
Many people delay retirement planning until later in life.
Starting early allows more time for long-term wealth accumulation and the potential benefits of compounding.
Ignoring Asset Allocation
Retirement planning should include an appropriate mix of investments rather than relying entirely on a single product.
Not Reviewing Investments
Financial goals and investment needs change over time.
Periodic reviews can help ensure that your retirement portfolio remains aligned with your objectives.
Frequently Asked Questions (FAQs)
Which is better: NPS or PPF?
Neither investment is universally better.
NPS may suit investors seeking market-linked growth, while PPF may suit those prioritizing stability and capital protection.
Can I invest in both NPS and PPF?
Yes.
Many investors use both products as part of a diversified retirement strategy.
Is NPS riskier than PPF?
Yes.
NPS includes exposure to market-linked investments, while PPF offers government-backed returns.
Which investment has a longer lock-in period?
PPF has a 15-year maturity period.
NPS is generally intended for retirement and follows withdrawal rules applicable to retirement savings.
Which offers potentially higher returns?
NPS may offer higher long-term return potential because of its exposure to equity and debt markets.
However, returns are not guaranteed.
Is PPF completely safe?
PPF is backed by the Government of India and is generally considered one of the safer long-term savings options available.
Advantages of NPS
✓ Retirement-focused investment.
✓ Potential for market-linked growth.
✓ Diversified investment portfolio.
✓ Tax benefits under applicable provisions.
✓ Suitable for long-term investors.
Advantages of PPF
✓ Government-backed investment.
✓ Stable long-term savings.
✓ Low-risk investment option.
✓ Section 80C tax benefits.
✓ Suitable for conservative investors.
Final Verdict
Both NPS and PPF are excellent long-term investment options, but they serve different purposes.
NPS focuses on retirement wealth creation through market-linked investments, making it suitable for investors who are comfortable with some level of risk.
PPF emphasizes capital safety, stable returns, and disciplined long-term savings, making it an attractive option for conservative investors.
For many individuals, the best approach may not be choosing one over the other but using both as part of a well-diversified financial plan.
Conclusion
Choosing between NPS and PPF depends on your retirement goals, risk tolerance, and investment strategy.
If you seek higher growth potential and are comfortable with market fluctuations, NPS may be a suitable option.
If you prioritize safety and predictable returns, PPF may better align with your financial objectives.
Review your financial plan regularly and select investments that support your long-term retirement needs rather than focusing only on short-term returns.
Disclaimer: This article is intended for educational purposes only and should not be considered financial, investment, or tax advice. Investment returns, tax benefits, withdrawal rules, and government regulations may change over time. Please consult a qualified financial advisor or tax professional before making investment decisions.